Desk Report
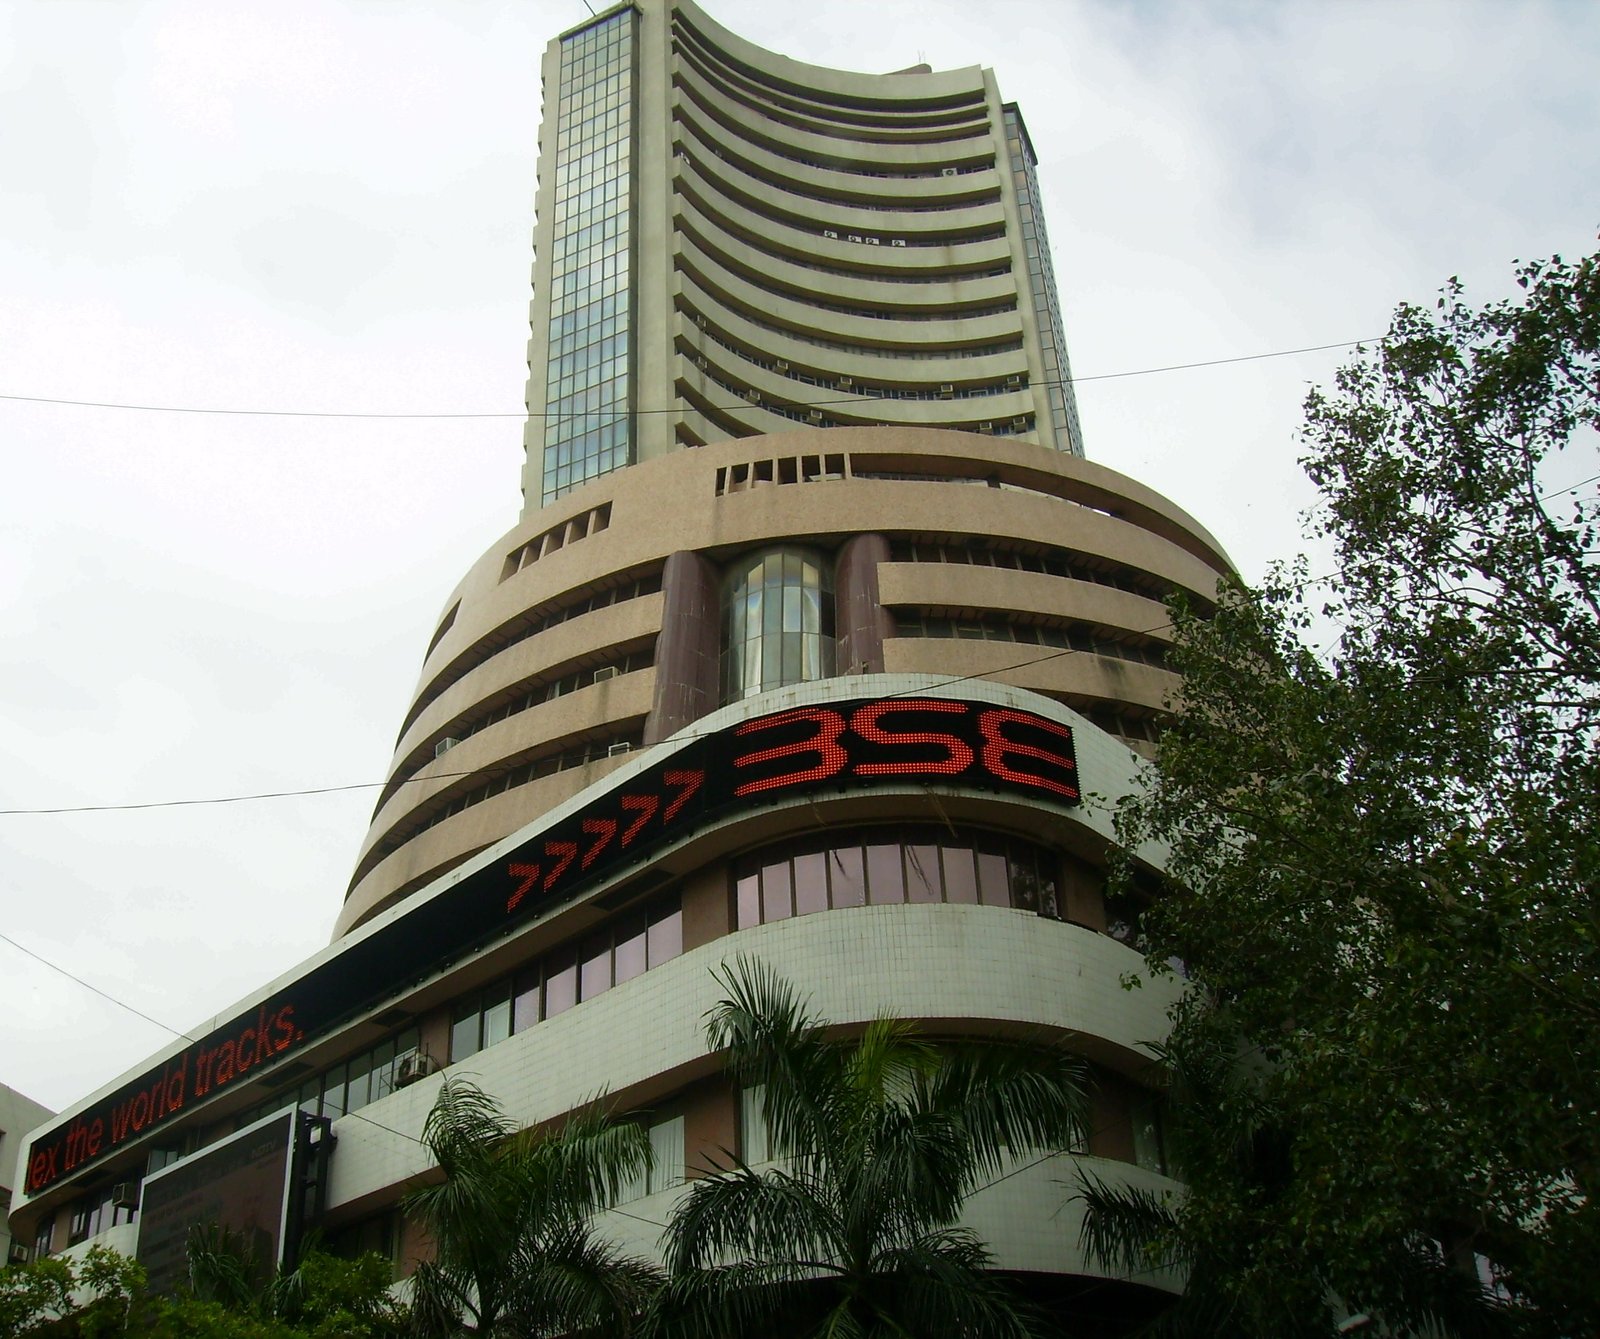
Indian equities stretched the Sensex Nifty weekly gains to a third consecutive week, with the Sensex rising 564.43 points to 81,592.45 and the Nifty 50 adding 113.95 points to 25,144.30, as smallcap stocks jumped 3.6 per cent and public-sector bank shares surged 7.5 per cent on sustained foreign buying.
Indian stock markets closed a holiday-shortened week with their third straight weekly gain, holding on to the advance even after a bout of profit-booking on Friday pulled both benchmarks lower. The gains came despite worries over rising inflation and crude oil prices, and they were powered above all by foreign investors, who bought Indian equities for a third week in a row. Broader markets did even better than the headline indices, with small and mid-sized stocks leading the advance for a third consecutive week.
Sensex Nifty Weekly Gains: The Numbers Behind the Third Straight Rise
For the week ended Friday, 13 November 2026, the BSE Sensex gained 564.43 points, or 0.69 per cent, to close at 81,592.45, while the NSE Nifty 50 advanced 113.95 points, or 0.45 per cent, to settle at 25,144.30. It was the third consecutive weekly advance for both benchmarks, a run not seen since June 2026, and it came in a Diwali holiday-shortened trading week. The Nifty crossed the 25,400 mark during the week for the first time since February 2026, before easing back. Friday itself was a weak session: the Sensex fell 318.56 points, or 0.39 per cent, and the Nifty slipped 155.05 points, or 0.61 per cent, snapping a three-session winning streak as traders booked profits and fretted over elevated crude oil prices and inflation.
The Sensex Nifty weekly gains were therefore built in the first four sessions of the week and defended on Friday, rather than extended into the close. That pattern — strong early momentum, a soft finish — has marked much of the recent rally, and it left the benchmarks higher for the week even as the final session turned red.
Smallcaps and Midcaps Outperform for a Third Week
Broader markets outperformed the benchmark indices for the third consecutive week, with buying in banking, financial services, realty and capital-market stocks helping Indian equities extend their winning streak. The Nifty Smallcap 100 index rose 3.6 per cent during the week ended 13 November, while the Nifty Midcap 100 gained over 2 per cent. Both indices recorded their third consecutive weekly advance, a sign that risk appetite has spread well beyond the large, index heavyweights.
Among midcaps, the week’s strongest performers rose between 10 and 18 per cent, led by Kalyan Jewellers India, PB Fintech, Hitachi Energy India, Bank of India, Motilal Oswal Financial Services and GE Vernova T&D India. In the smallcap space, the leaders included Data Patterns (India), Aditya Birla Real Estate, Netweb Technologies India, Navin Fluorine International and Meesho. The breadth of the rally matters because it shows the buying was not confined to a handful of large stocks: money moved into smaller companies too, which usually happens only when investors are confident enough to take on more risk.
PSU Banks Lead the Sectoral Rally; IT the Only Loser
On the sectoral front, the Nifty PSU Bank index led the rally with a gain of 7.5 per cent during the week. State Bank of India, Punjab National Bank and Bank of Baroda led the gains earlier in the week, as investors bet that public-sector lenders would benefit from steady credit growth and improving balance sheets. The Nifty Media index advanced 5.2 per cent and the Nifty Capital Markets index rose 3.8 per cent, tracking the broader enthusiasm for financial stocks.
The Nifty IT index was the only sectoral laggard, declining 3.7 per cent during the week. Technology stocks came under pressure as global concerns over artificial-intelligence valuations spilled into Indian markets, and the sector’s fall stood out against gains almost everywhere else. On Friday itself, auto, realty and metal stocks each fell about 1 per cent, adding to the day’s profit-booking mood.
Foreign Buying Powers the Rally; Domestic Institutions Sell
Foreign institutional investors extended their buying streak to a third consecutive week, purchasing equities worth Rs 33,342.70 crore during the week. The buying came after a ten-week selling phase by foreign investors, and it has now run for three straight weeks. On Friday alone, foreign investors bought shares worth Rs 5,736.55 crore on a provisional basis, their tenth consecutive session of net buying. Provisional exchange data put total foreign inflows into Indian equities in November past $8 billion, the highest monthly total since December 2020.
Domestic institutional investors moved the other way. They remained net sellers for the second straight week, offloading shares worth Rs 24,191.81 crore. The contrast is the week’s clearest divide: foreign money flowed in while domestic institutions booked profits. That foreign buying, rather than domestic support, carried the indices to their third straight weekly gain — and it is also why the rally’s durability will depend heavily on whether those flows continue.
Tata Motors and the Earnings Backdrop
The week also brought a strong set of September-quarter numbers from Tata Motors, whose electric-vehicle sales jumped 90 per cent even as revenue hit a record Rs 20,423 crore, while electric-car sales in the country crossed the three-lakh mark. The results added to the sense that corporate earnings are holding up, which has been one of the supports for the market through the recent rally. For the full story, read our report on the Tata Motors results. The last time Indian equities put together a weekly rally of this kind, the Sensex surged 1,718 points in Dhanteras week — the strongest weekly rally since 2021.
Inflation and the Rupee Temper the Cheer
Not everything in the week’s data was comfortable. India’s retail inflation rose to 6.09 per cent in October, up from 5.54 per cent in September and above the Reserve Bank of India’s upper tolerance limit of 6 per cent, as food prices increased. A stronger-than-expected reading on consumer inflation in the United States reinforced expectations of another Federal Reserve rate increase in December, while hawkish comments from Fed officials pushed global bond yields higher. Both developments weighed on sentiment in the final session of the week.
The rupee added to the caution. In a volatile week, the Indian currency depreciated 33 paise to close at 94.24 per dollar on 13 November, compared with 93.91 at the previous week’s close. Higher global bond yields and the rebound in crude oil prices pressured the currency. Brent crude traded around $95.70 to $95.84 a barrel on Friday, down about 2.5 per cent for the week; falling crude earlier in the week had been one of the supports for the rally, and its late-week rebound helped trigger Friday’s profit-booking.
What to Watch Next Week
Whether the Sensex Nifty weekly gains stretch to a fourth week will depend on a handful of triggers. Investors will track wholesale inflation data at home, quarterly results from chipmaker Nvidia, the minutes of the US Federal Reserve’s latest meeting, and the direction of crude oil prices. Above all, they will watch whether foreign investors keep buying: ten straight sessions of net purchases have carried the market this far, and a pause in those flows would leave the rally without its main support.
Analysts cited in market reports see support for the Nifty at 24,800 to 25,000 and resistance at 25,400, the level the index touched during the week before pulling back. With inflation above the central bank’s tolerance band and global rates still a source of uncertainty, the coming week is likely to stay volatile. For now, though, the scoreboard is clear: three straight weekly gains, smallcaps up 3.6 per cent, PSU banks up 7.5 per cent, and foreign buyers still firmly in the market.
This is a factual account of the week’s market movements, not investment advice. Prices and flows cited here are closing figures for the week ended 13 November 2026.
Disclaimer: This report is based on available sources and verification. If any fact is found to be incorrect, a correction will be published.